

REALOGIS: Large-scale spaces characterise Berlin's logistics real estate market – demand base remains stable
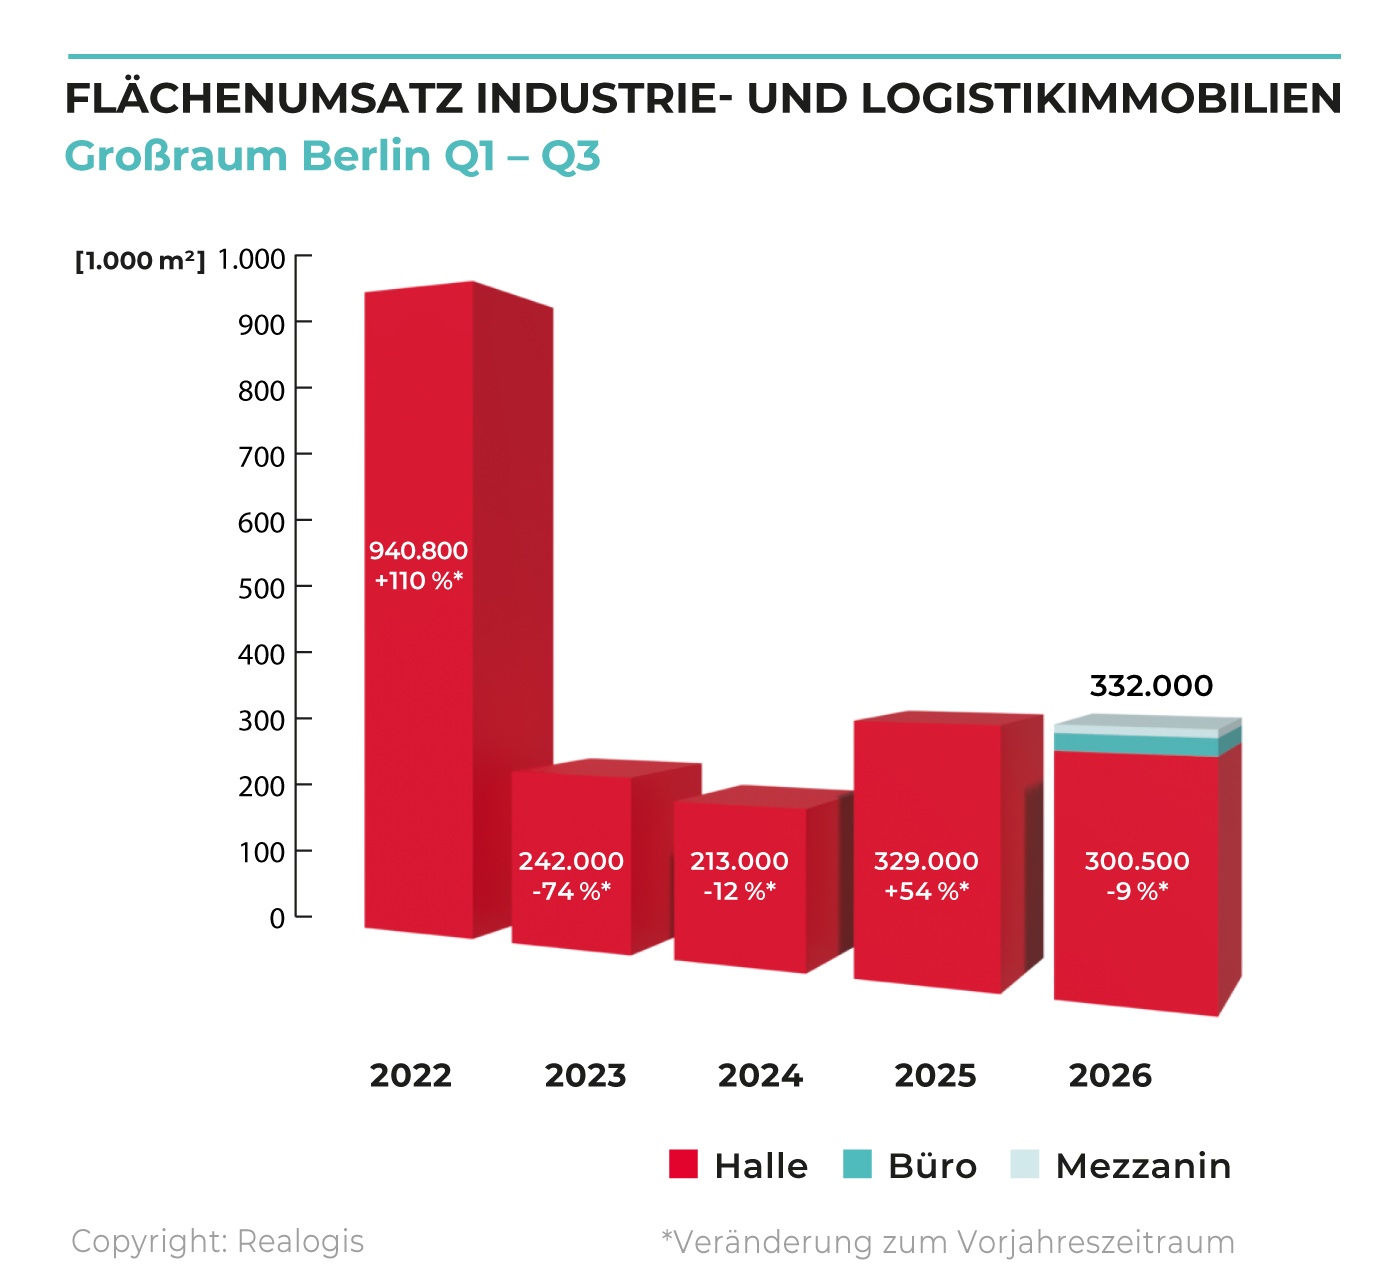
- Total take-up in the first three quarters of 2026 at 332,000 m²
- Hall turnover down 9% compared to the strong prior-year period
- Prime and average rents stable at a high level
- Existing properties were the type of property with the highest turnover
- Logistics companies took up the most space
Berlin, 7 October 2026 – In the first three quarters of 2026, the REALOGIS Group, Germany's leading consulting firm for industrial and logistics real estate as well as commercial properties, recorded take-up of a total of 332,000 m² on the Berlin logistics and industrial real estate market. Of this, 300,500 m² or 91% was hall space, which corresponds to a decrease of 9% compared to the high-turnover period of the previous year (329,000 m²). In addition, 21,400 m² (6%) was office space and 10,100 m² (3%) mezzanine space.
The five largest deals of JD Logistics with 41,430 m² and 28,070 m², ASML with 27,000 m², TACWRK with 14,000 m² and acut fulfillment with 11,520 m² accounted for 37% of total take-up.
Alexander Ego, Managing Director of REALOGIS Immobilien Berlin GmbH, comments: "The high concentration of market activity on a few large-volume deals is remarkable. At the same time, it is clear that companies from the logistics and retail sectors in particular continue to consistently implement their space requirements despite the high rent level. The broad distribution of the remaining deals across the size classes also suggests that demand is sustainable overall."
Renting: Stability at a high level
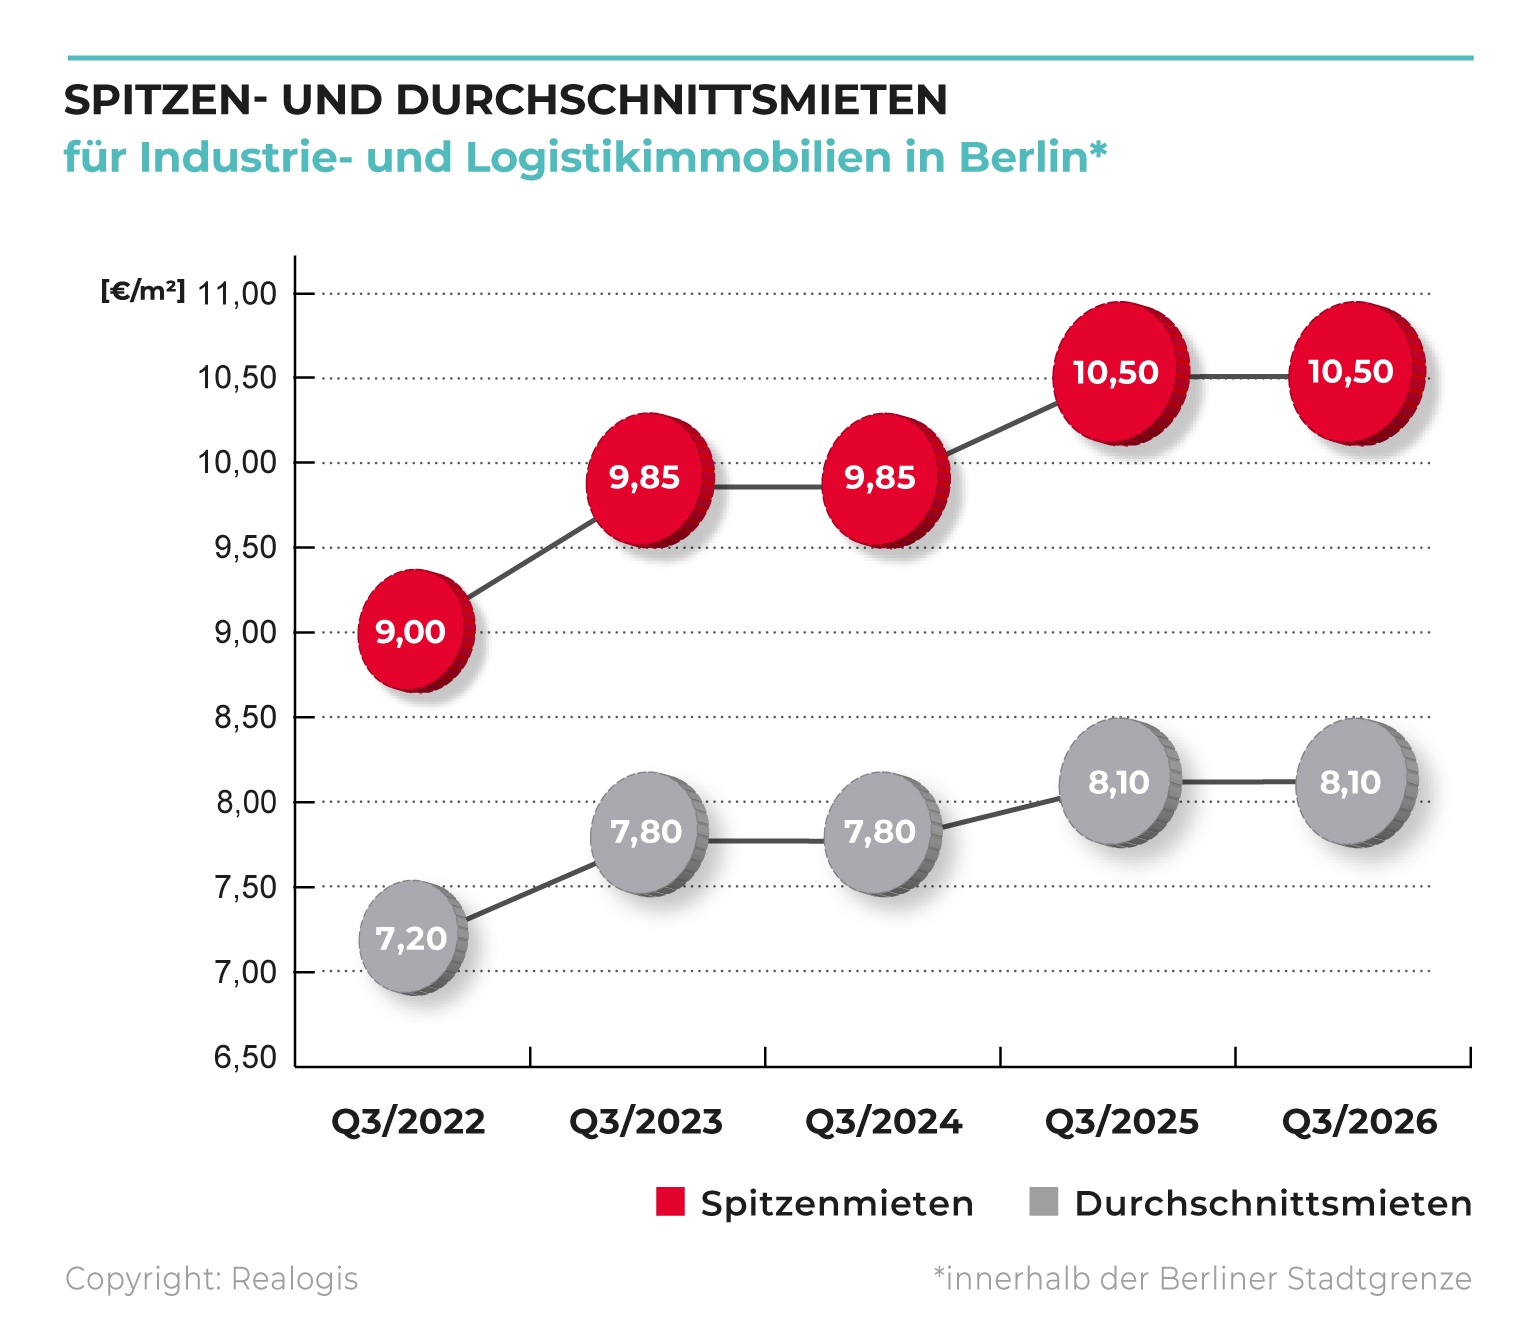
At €10.50/m² at the end of the third quarter, the prime rent remained at the same level as in the same period last year. It was thus 6% above the current 5-year average of €9.94/m². The average rent also remained at €8.10/m², exceeding the 5-year average of €7.80/m² by 4%. Both rental values have recently shown a stable development at a consistently high level.
Types of space: Existing properties were clearly in the lead
At 190,200 m² or 57% of total take-up, the largest share was accounted for by existing properties. The three deals concluded by JD Logistics, TACWRK and acut fulfillment together contributed 53,590 m² and thus accounted for 28% of the take-up of the portfolio.
Leases in new buildings on former brownfields reached 103,900 m² or 31%. Almost two-thirds of this volume was accounted for by the deals of JD Logistics with 41,430 m² and ASML with 27,000 m². Newbuildings on greenfield sites accounted for 37,900 m² or 12% of total take-up.
By type of building, big-box space dominated with 243,100 m² or 73%. Business parks accounted for 48,600 m² or 15%, while other properties accounted for 40,300 m² or 12%. Leases accounted for 283,700 m² or 85% of take-up. Owner-occupiers accounted for 48,300 m² or 15%.
Regions: Berlin city retains top position
The Berlin urban area was the region with the highest take-up with 153,600 m² or 46%. Within the urban area, Berlin Süd was at the top with 80,900 m² (53%). The deals of JD Logistics and ASML totalled 55,070 m² there, accounting for 68% of take-up. Berlin North followed with 25,700 m² (17%), just ahead of Berlin West with 25,300 m² (16%) and Berlin East with 21,700 m² (14%).
The Berlin Southern Countryside followed in second place with 134,300 m² or 41%. The deals with JD Logistics, TACWRK and acut fulfillment contributed a total of 66,950 m² there. The West Berlin Surrounding Area reached 24,100 m² (7%), the Berlin North Area 20,000 m² (6%). No letting deals were recorded in the East Berlin Surrounding Area.
Industries: Logistics and freight forwarding before retail
Logistics and freight forwarding companies achieved the highest take-up of space with 119,400 m² or 36%. The two JD Logistics deals and the acut fulfillment deal accounted for 81,020 m² or 68% of the industry's turnover.
Retail followed with 90,500 m² or 27%. Of this, 59,200 m² (65%) was accounted for by traditional retail and 31,300 m² (35%) by e-commerce. At 14,000 m², TACWRK accounted for almost a quarter of take-up in traditional retail.
Industry and production took third place with 69,600 m² or 21%. ASML's closing of 27,000 m² accounted for 39% of the industry's turnover. The "Other" category accounted for 52,500 m² or 16%.
Size classes: Almost every second square metre was accounted for by large areas
Large spaces of 10,001 m² or more dominated the market with 163,100 m² or 49% of total take-up. The five largest deals accounted for 75% of the volume in this size class.
Spaces between 5,001 and 10,000 m² followed with 68,900 m² or 21%. This means that 70% of the total take-up was accounted for by deals of 5,001 m² or more. The segment between 3,001 and 5,000 m² reached 50,600 m² (15%). Areas between 1,000 and 3,000 m² accounted for 37,600 m² (11%). The smallest areas under 1,000 m² accounted for 11,800 m² (4%).
Key figures at a glance
- Take-up 332,000 m²
- Top rent 10.50 €/m²
- Average rent 8.10 €/m²
- Existing properties 190,200 m² | New building on brownfield 103,900 m² |
New building on a greenfield site 37,900 m²
- Tenants 283,700 m² | Owner-occupiers 48,300 m²
REALOGIS. The No. 1 in industrial and logistics real estate
The REALOGIS Group is Germany's leading address for consulting and brokerage of industrial and logistics properties as well as commercial properties. As an owner-managed company with locations in Berlin, Düsseldorf, Germany South/North, Frankfurt am Main, Hamburg, Leipzig, Munich and Stuttgart, the company, which was founded in 2005, has in-depth market knowledge and more than twenty years of experience in the German real estate sector.
Around 70 employees support national and international companies from logistics, industry, trade and e-commerce as well as private and institutional investors. The range of services includes the placement of tenants for existing and new properties, the support of investors in acquisitions and project developments, advice on the search for or sale of land as well as the development and implementation of holistic real estate strategies, from location analysis to the realisation of assets that are no longer necessary for operation.
Contact Media
Targa Communications
Arne Degener
T +49 151 196 933 90
E ad@targacommunications.de
Latest Warehouse News
REALOGIS: Large-scale spaces characterise Berlin's logistics real estate market – demand base remains stable
Total take-up in the first three quarters of 2026 at 332,000 m² + Hall turnover down 9% compared to the strong prior-year period + Prime and average rents stable at a high level + Existing properties were the type of property with the highest turnover + Logistics companies took up the most space...
NAGEL-GROUP puts new logistics site in Rostock into operation
The Nagel-Group is further expanding its logistics network in northern Germany and has moved into a new logistics property in VGP Park Rostock...
Logistics investment volume again exceeds € 4 billion
BNP Paribas Real Estate publishes market figures for Q3 2026...
Logix publishes new study on multilevel logistics real estate
Potentials, basic types and challenges at a glance + Typing creates the basis for future standards...